

Fraud teams are being asked to accomplish more with limited resources. They’re expected to adopt AI, manage increasingly complex threats, protect the customer experience, and demonstrate measurable business value, often without additional headcount or budget.
As AI changes how fraud teams operate, leaders face difficult decisions about where to invest, which skills to prioritize, and how to make the most of existing resources. Building a successful fraud program requires more than keeping losses low. It means showing how fraud prevention supports the company’s broader goals.
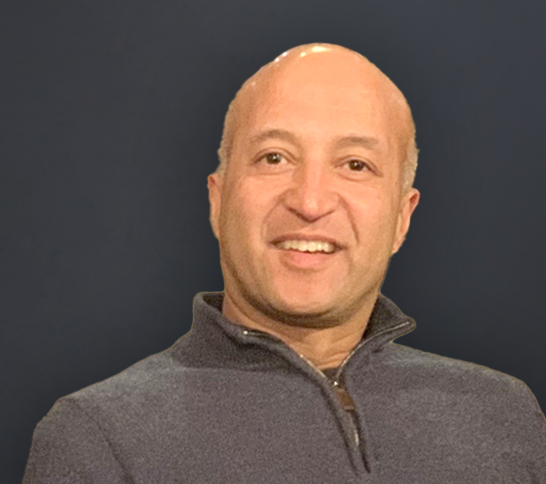
In a recent episode of The Blueprint, Sift’s practical series for fraud leaders, Sift Field CTO Kevin Lee joined trust and safety leader Barrington Lloyd-Lovett and host Jerry Hoff to discuss How to Build a Fraud Team That Earns Its Investment.
The conversation explored how AI is reshaping fraud operations, what executives want to see before approving investments, and how to build adaptable teams that deliver lasting value. Here are five key takeaways.
1. Start AI adoption with repetitive, time-consuming work
AI presents an opportunity to increase fraud team productivity, particularly in workflows that require extensive manual data collection and analysis. Analysts often spend valuable time gathering information from different systems before they can begin evaluating risk. AI agents can accelerate that process by collecting data, identifying patterns, and summarizing findings.
“AI is effectively a tool that we use to do things that we can do, but faster and more broadly,” explained Barrington Lloyd-Lovett.
The best starting points are high-volume, repeatable tasks where automation can deliver measurable efficiency gains. These might include aggregating account activity, preparing investigation summaries, or surfacing relevant signals across multiple systems.
Starting with well-defined use cases also makes it easier to evaluate performance before expanding into more complex workflows. Fraud leaders should identify where manual processes create bottlenecks, determine which tasks can be automated reliably, and measure improvements in investigation speed and team capacity.
2. Develop AI skills without losing foundational fraud expertise
As AI takes on more routine tasks, the skills required to run a successful fraud operation are changing. Analysts will increasingly need to direct automated workflows, evaluate AI-generated findings, and improve system performance. At the same time, teams still need the investigative expertise to recognize suspicious behavior and challenge inaccurate conclusions.
“On some level, if people don’t understand the core work, then they won’t be able to build, use, manage the agents,” said Lloyd-Lovett.
Overreliance on automation creates risks, particularly when employees lack the experience to recognize incorrect or incomplete assessments. Human oversight remains especially important for consequential decisions, including account restrictions, sensitive investigations, and fraud policy changes.
As Kevin Lee explained, “anything that’s high stakes and involves irreversible decisions that might come into policy or strategy discussions, we still need humans in that mix.”
The next generation of fraud professionals will need investigative knowledge, technical fluency, and critical thinking. Training programs should develop these capabilities together so employees can use AI effectively while retaining the judgment necessary to manage risk.
3. Set realistic AI expectations and demonstrate measurable results
AI has become a major executive priority, but expectations about its capabilities and immediate impact vary considerably.
“When I speak with C-suite folks, or really anybody, on AI, there is wild speculation and expectations as to what AI can do and what it can’t do,” observed Jerry Hoff.
For fraud leaders, securing support for AI investments means connecting technology to measurable business outcomes. Rather than proposing broad transformation initiatives, focus on specific workflows. Compare how a task is performed today with how it could operate using AI, then quantify the expected improvements.
Those improvements might include faster investigations, increased review capacity, lower operational costs, or the ability to support higher transaction volumes without proportionally increasing headcount.
Setting realistic expectations is equally important. AI initiatives require experimentation, testing, and ongoing quality control. Initial efficiency improvements of 20% to 30% can represent meaningful progress, depending on the workflow, even if they fall short of more ambitious projections.
For growing businesses, the greatest value may come from enabling existing teams to handle more activity while maintaining strong fraud prevention performance. A successful business case should clearly outline the problem, expected improvement, investment requirements, and how results will be measured.
4. Build a stronger business case by presenting options and tradeoffs
Securing additional fraud prevention resources requires more than demonstrating that a team is overwhelmed. Executives need to understand what the investment will accomplish, how it compares with alternatives, and why it deserves priority.
“When you ask for more resources, you need to be able to speak to what the expected return is and should be,” said Lloyd-Lovett.
Consider a team facing growing investigation queues. Hiring analysts may be one solution, but alternatives include automating repetitive tasks, improving workflows, or outsourcing selected activities. Each approach carries different costs, benefits, and operational implications.
Before proposing new technology, fraud leaders should also assess whether they’re fully utilizing existing tools. Underused capabilities and inefficient processes may create opportunities to increase capacity without additional investment.
When communicating with executives, focus on the expected return and its connection to broader business priorities. Fraud prevention investments can support revenue growth by reducing false positives, improve operational efficiency, or protect against financial losses.
Strong proposals also explain the tradeoffs of inaction. Which activities will be delayed or deprioritized without additional resources? What risks could increase? Answering these questions helps executives make informed decisions and positions fraud leaders as strategic business partners.
5. Build adaptable teams that can deliver value as priorities change
Fraud operations must continuously adjust to changing threats, technology, and business priorities. That flexibility becomes especially important during hiring freezes, budget reductions, or organizational changes.
When evaluating workloads, focus on business impact rather than volume alone. A small number of complex investigations may prevent substantial losses, while some high-volume tasks may have less impact on overall risk.
“It comes down to mapping the work by risk and value, and not by volume,” said Lee.
Understanding these differences helps leaders determine where resources are most valuable and which activities can be streamlined, automated, or deprioritized. It also provides a clearer way to communicate the consequences of budget reductions.
Developing versatile teams is equally important. Fraud professionals who can learn new technologies and take on different responsibilities give organizations greater flexibility as operational needs evolve. An experienced analyst, for example, may be well positioned to help develop automated workflows or evaluate AI-generated findings.
When resources tighten, redeploying existing employees can preserve institutional knowledge while addressing emerging priorities. Investing in continuous learning helps teams adapt without needing to hire for every new capability.
Building a fraud team that delivers measurable business value
Fraud teams play an increasingly important role in business performance. Beyond preventing losses, they’re responsible for protecting legitimate customers, improving efficiency, and supporting secure growth.
Success requires a combination of technology, human expertise, and strategic resource management. AI can increase team capacity, but effective adoption depends on choosing the right workflows, maintaining investigative skills, and setting realistic expectations. Securing continued investment requires connecting fraud prevention efforts to measurable business outcomes.
As fraud operations evolve, teams that can adapt their skills, processes, and technology while demonstrating their value will be better positioned to support long-term growth.
Want more practical guidance on building a high-performing fraud team? Watch the full session, How to Build a Fraud Team That Earns Its Investment, and explore more episodes of The Blueprint.